

GO2bank: Mobile banking
by Green Dot
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
I approached GO2bank: Mobile banking as a practical finance app rather than as a replacement for every kind of bank account. That distinction matters. Its appeal is the ability to handle everyday money tasks from a phone, with Green Dot behind the service and a free download for users who want a mobile-first banking experience. After spending time with the app, I found it most convincing as a straightforward account for routine spending, deposits, and basic money management, especially when convenience matters more than a large branch network.
The app has built a sizeable audience, with over 5 million installs and an average rating of 4.4 from around 105 thousand ratings. Those figures suggest that the central idea works for many people, but they do not remove the need to look closely at how the app fits your own financial habits. A mobile bank can be useful without being the best choice for someone who needs extensive budgeting tools, complex account products, or personal service in a branch.
How GO2bank feels in everyday use
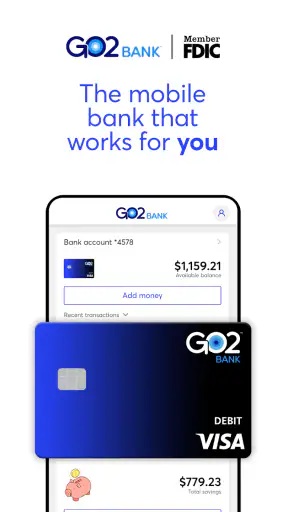
The first thing I noticed is that the experience is designed around quick decisions. I do not have to think of it as a full financial command center. Instead, I can open the app to check available money, review recent activity, and deal with ordinary banking tasks without navigating through a crowded desktop-style interface. That focus makes it approachable for someone who wants a clear view of day-to-day funds.
For a realistic example, imagine being paid and wanting to separate money for groceries, transport, and bills before the week gets busy. A mobile banking app is useful here because I can check the balance before making a purchase, review whether a payment has already cleared, and spot activity that does not look familiar. The benefit is not dramatic automation; it is reducing small moments of uncertainty that otherwise lead to overdrawing an account or forgetting a transaction.
I also like the fact that the service is free to download. That lowers the barrier to trying it, although “free” should not be interpreted as meaning that every possible banking action has no cost. Anyone considering it should read the applicable account terms and fee information carefully, particularly if they plan to use cash deposits, transfers, or services outside their normal routine. In finance, the practical cost of an app depends on how you use it, not merely on the download price.
The interface is better suited to people who prefer a phone over a branch or a traditional banking website. It keeps the main relationship with the account in one place, which is convenient when you are traveling, working irregular hours, or trying to avoid paper-based administration. On the other hand, users who enjoy sitting down at a computer to organize detailed finances may find a mobile-first approach less satisfying.
A useful second account, not automatically a complete financial home
In my opinion, one of the strongest ways to use GO2bank is as a controlled spending account. I can direct a planned amount toward regular expenses and keep the rest of my money elsewhere. This creates a simple boundary between money intended for immediate use and money reserved for longer-term needs. It is not a sophisticated envelope-budgeting system, but the separation itself can make spending decisions easier.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That setup is also helpful for people who want to reduce the number of times they expose a primary account to everyday purchases. If a card is used frequently for subscriptions, shopping, and travel, a dedicated account can make monitoring those transactions less overwhelming. The trade-off is that another account adds responsibility: I have to remember which account holds the money for a particular bill and keep both services updated.
Compared with a conventional bank, the main advantage is accessibility. A traditional institution may offer broader in-person support or a wider collection of products, but it can also feel slower for someone who only needs routine account access from a phone. Compared with a prepaid card, a mobile banking service may feel more like an account relationship, yet users should still examine the rules, funding methods, and available services before treating it as their only financial tool.
What the current version tells me about the product
The current version is 3.2.0, and the app supports devices running Android 9 or later. Those details are useful when deciding whether an older phone can run it, especially if the device is kept for banking because it has a separate number or a less cluttered setup. I would update the operating system where possible and avoid relying on a phone that no longer receives security updates, regardless of how well the app itself performs.
The version number also gives a small but important clue about expectations. This is an established product rather than a brand-new experiment, yet a version label alone does not tell me that every desired feature has arrived or that every user will see identical behavior. Banking apps evolve gradually, and changes can affect navigation, verification steps, alerts, or the way a transaction is displayed. I recommend checking the screen carefully after an update instead of assuming that a familiar workflow has stayed exactly the same.
Green Dot’s role as developer matters because the app is tied to a financial service, not simply a decorative balance tracker. That means account access, identity checks, transaction records, and support pathways are more important than visual polish. When I review a finance app, I pay attention to whether it helps me understand what happened with my money. A clean screen is useful, but accurate status information and a dependable way to resolve a problem matter more.
Small habits that make the app more useful
My first practical tip is to turn checking the activity list into a short routine rather than waiting for a problem. I would review it after a cluster of purchases, after a recurring payment, and whenever money is added. This makes unfamiliar activity easier to notice because I still remember what I actually did. It also prevents a common mistake: seeing a lower balance and assuming the app is wrong when a pending transaction has simply changed the amount available to spend.
A second useful workflow is to decide in advance what the account is for. If I use it for groceries and transport, I can judge every transaction against that purpose. If I use it for bills, I can check the account before due dates rather than moving money in a panic. The app cannot create discipline on its own, but a narrow purpose turns a general banking screen into a simple control panel.
Third, I would keep a separate record of important payment dates even if the app displays transactions clearly. A transaction history tells me what has happened; it does not necessarily replace my own calendar for what must happen next. This is especially important when income arrives on an irregular schedule. A mobile banking app can show the current situation, but planning still belongs to the user.
Finally, I would treat notifications and security prompts as part of the banking experience rather than as annoyances to dismiss automatically. On a finance app, an unexpected sign-in request or an unfamiliar transaction deserves attention. I would use a strong device lock, avoid signing in on shared phones, and install updates through the official app store. These are simple habits, but they matter more than a minor difference in interface design.
Where the experience can become frustrating
The biggest limitation is the same feature that makes the product attractive: it is mobile-first. If I need to compare many months of activity, prepare a detailed household budget, or manage several financial goals at once, a dedicated budgeting service or a full bank website may be more comfortable. A phone screen is excellent for quick checks, but less pleasant for analysis that requires side-by-side comparisons.
There is also a mental cost to depending on a digital service. When everything works, checking an account from a phone feels effortless. When access, verification, or a transaction requires extra attention, the lack of a nearby branch can feel more significant. I would not choose this kind of banking arrangement for someone who strongly prefers face-to-face help or who is uncomfortable resolving account questions through digital support channels.
Another trade-off is that convenience can encourage passive money management. Because the balance is always visible, I may feel informed without actually having a plan. GO2bank can help me monitor activity, but it does not turn a low balance into a solution, and it cannot decide which expenses should be reduced. Users looking for deep financial coaching, investment management, or advanced household planning should compare it with services built specifically for those needs.
I would also be cautious about making it the only account for an important payment until I understand the complete workflow. Before moving a paycheck or a critical bill, I would test smaller amounts, confirm how transactions appear, and make sure I know how to obtain help if something is delayed or disputed. That is not a criticism unique to this app; it is sensible with any digital financial service. The consequences of a banking mistake are more serious than the inconvenience of a missed entertainment subscription.
Who should use it, and who should look elsewhere
I think the app is a good match for someone who wants basic banking access without making a branch visit part of every routine. It can suit a person managing everyday spending, a user who wants a separate account for controlled expenses, or someone who prefers checking money from a phone. It may also help users who are comfortable learning through a focused interface instead of asking staff to handle ordinary tasks.
I would be more hesitant to recommend it as the sole financial hub for a person with complicated needs. If you require extensive account types, detailed investment tools, business banking, or frequent in-person assistance, a traditional bank may be a better foundation. If your main goal is building a detailed spending plan across several institutions, a specialized budgeting app may offer stronger analysis. If you mainly need a card for occasional purchases, compare the account structure and terms with simpler alternatives before opening anything.
The age rating is Everyone, which makes the app broadly accessible from a content perspective. That does not mean every financial situation is equally suitable for it. A younger or inexperienced user may still need guidance about account security, payment timing, and fees. The app can make access easier, but financial responsibility does not become simpler merely because the interface is on a phone.
How it compares with familiar alternatives
Against a large traditional bank, GO2bank feels more direct and less tied to physical service. I value that when I want to check a balance quickly or keep routine spending separate. The traditional bank has the advantage when I want a broader relationship, more product depth, or help that is easier to obtain in person. The better choice depends on whether speed and mobile access outweigh breadth and personal support.
Against a prepaid product, the comparison is more nuanced. Both can be attractive to people who want to control spending, but I would not assume that similar card-based behavior means identical account rules. I would compare how money is added, how transactions are handled, what support is available, and which everyday uses are important to me. A familiar brand name is not a substitute for reading the terms.
Against a budgeting app, GO2bank serves a different purpose. A budgeting tool usually helps me see patterns across accounts, while this service is centered on accessing and using the account itself. I would not expect it to replace a dedicated planning system if I need category trends, long-term targets, or a complete household overview. Used together, however, a banking app and a budgeting tool can complement each other: one shows the account’s activity, while the other helps interpret it.
What existing users should expect from ongoing changes
For current users, the most important effect of product evolution is usually not a dramatic new feature but a change in familiar steps. A revised menu can make a common task faster or force me to relearn where it lives. After updating, I would check the balance display, transaction details, deposit or transfer screens, security settings, and notification preferences. Those are the areas where a small interface change can affect daily confidence.
I would also avoid judging an update solely by its appearance. A cleaner screen is welcome, but I want to know whether it makes pending activity easier to understand, reduces unnecessary taps, or gives clearer feedback when an action is incomplete. If an update changes wording around a transaction, I would read it carefully rather than relying on memory. Financial language deserves more attention than the labels in a typical social app.
The current release gives users a reasonable basis for expecting a maintained mobile experience, but I would keep expectations practical. Version progress does not guarantee that every limitation disappears. The right question is whether each change improves the tasks I actually perform. Someone who only checks spending may notice little, while a user who deposits money or manages recurring payments may feel every workflow adjustment.
What I would like to see watched closely
When evaluating future changes, I would watch for clearer explanations around transaction status and account availability. The difference between money that has arrived, money that is pending, and money that can actually be spent is central to avoiding mistakes. Any improvement that makes those distinctions more obvious would have real value, even if it is less exciting than a visual redesign.
I would also watch how the app handles support during unusual situations. Routine banking is easy to judge, but the real test comes when a card, deposit, transfer, or sign-in does not behave as expected. A useful future improvement would be guidance that helps users understand the next step without making them search through unrelated screens. For me, dependable problem-solving is more important than adding decorative features.
Finally, I would pay attention to whether the app remains comfortable on supported older devices while still keeping security current. Supporting Android 9 or later is helpful for people who do not replace phones frequently, but compatibility and security must develop together. Users should keep their device updated where possible and should not postpone an important security update simply because the current interface feels familiar.
After using it, my view is positive but specific: this is a practical mobile banking option, not a universal answer to financial management. I appreciate the focused access, the free entry point, and the usefulness of keeping everyday money visible in one place. I would recommend it to a friend who wants a phone-centered account for ordinary spending and is willing to understand the terms and maintain good security habits.
I would not recommend opening it blindly as a replacement for every existing financial service. First decide what job the account must perform, then test that workflow carefully and compare it with a traditional bank, a prepaid alternative, or a budgeting tool where appropriate. For the right user, GO2bank: Mobile banking can make routine money management feel less cumbersome. Its real strength is not that it solves every financial problem, but that it puts everyday account control within easy reach when that is exactly what you need.
Pros
- No monthly fee when qualifying for the required direct deposit
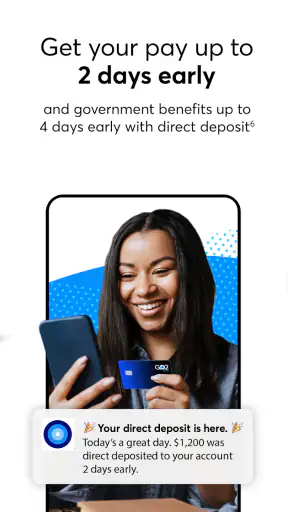
- Early direct deposit may provide access to eligible paychecks sooner
- Cash deposits are available at many participating retail locations
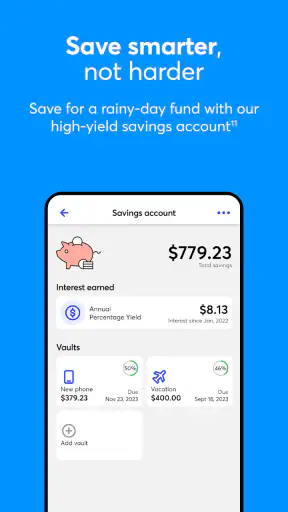
- Built-in savings tools can help organize money and build an emergency fund
- Visa debit card includes useful controls for managing spending and security
Cons
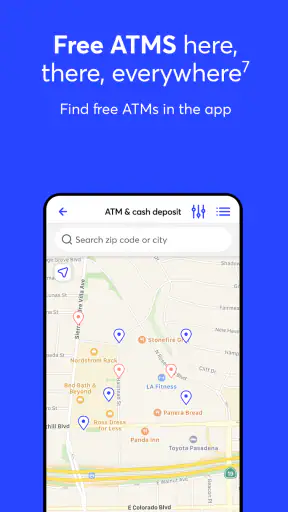
- Out-of-network ATM withdrawals can incur additional fees
- Cash deposit limits and retailer availability may vary by location
- Some features require identity verification and eligibility approval
- Customer support options may feel limited compared with traditional banks
- The app is not a full substitute for accounts offering loans or extensive banking services
FAQs for GO2bank: Mobile banking
What is GO2bank, and who can use the app?
GO2bank is a mobile banking app designed for managing everyday finances from an Android or iOS device. After opening an account, users can typically view balances, receive direct deposits, pay bills, transfer money, deposit checks, and use a GO2bank debit card. Availability and eligibility may depend on U.S. residency, identity verification, age requirements, and the account terms in effect when you apply.
Is GO2bank free to use, or are there fees?
GO2bank may offer useful banking services without a traditional monthly maintenance fee, but the account is not completely fee-free in every situation. Potential charges can include out-of-network ATM withdrawals, cash deposits at participating retailers, expedited services, overdraft-related features, or other optional transactions. Before downloading or using the app, review the current fee schedule and account disclosures carefully, since fees and conditions can change.
Can I deposit money and receive my paycheck through GO2bank?
Yes, GO2bank supports several ways to add money, including direct deposit for paychecks or government benefits, bank transfers, mobile check deposit where available, and cash deposits at participating retail locations. Direct deposit may provide earlier access than a standard payday, but timing is not guaranteed and depends on when the payer submits the deposit. Deposit limits, eligibility rules, and retailer fees may apply.
How secure is the GO2bank mobile banking app?
GO2bank uses common mobile-banking security measures such as account authentication, encrypted connections, transaction monitoring, and options like device-based login or biometric verification when supported by your phone. However, no financial app is completely risk-free. Use the official app store, keep your operating system updated, avoid sharing verification codes, and contact GO2bank promptly if you notice suspicious activity or lose access to your device.
What should I know about the GO2bank debit card and overdraft protection?
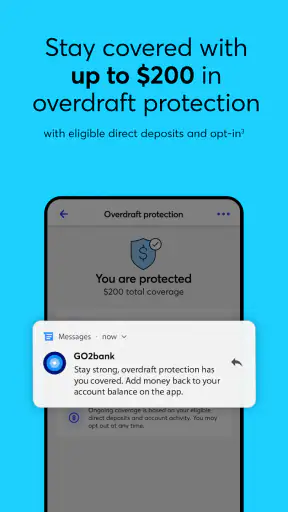
The GO2bank account generally includes access to a debit card that can be used for purchases and eligible ATM withdrawals, subject to the account agreement and network availability. The app may also provide overdraft protection features for qualifying users, but approval, limits, repayment conditions, and fees can vary. Read the current disclosures before relying on overdraft coverage for essential payments or recurring expenses.

GO2bank: Mobile banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via appsupport@GO2bank.com, visit http://www.GO2bank.com/, or review their https://www.go2bank.com/agreements/technology-privacy-statement.










